-
PRODUCTS & SERVICESOptimized cooling solutions for modern data centersProducts & ServicesOptimized cooling solutions for modern data centers
-
CAPABILITIESAdvancing liquid cooling technologiesCapabilitiesAdvancing liquid cooling technologies
-
TechnologiesLiquid Cooling InnovationTechnologiesLiquid Cooling Innovation
-
RESOURCESLatest News & InformationResourcesLatest News & Information
-
ABOUTOur history, leadership and ownershipAboutOur history, leadership and ownership
-
CONTACTFacility locations and global operational footprint

Top 10 Rubber Timing Belts Manufacturers Worldwide
Rubber Timing Belts keep engines, conveyors, packaging machines, and robotic systems synchronized. Their teeth must engage cleanly with matching pulleys. A small mismatch can create vibration, noise, or costly downtime. This article introduces the Top 10 Rubber Timing Belts Manufacturers Worldwide and examines what separates dependable suppliers from ordinary producers.
Dr. Robert W. Thomson, a respected belt-drive engineering author, stated, “A timing belt transfers motion through positive tooth engagement, not friction.” That principle remains practical today. Buyers should examine rubber compound quality, tooth accuracy, tensile cords, temperature resistance, and documented testing. Manufacturer experience also matters. A supplier that understands oil exposure, dust, repeated bending, and sudden loads can recommend a safer belt profile.
The ranking considers product range, manufacturing capability, quality control, technical support, and global availability. It also recognizes that “largest” does not always mean “best.” A smaller specialist may deliver better customization or faster engineering support. That difference is easy to miss.
Real-world performance tells the deeper story. A belt running inside a warm machine cabinet faces different demands than one operating near coolant spray. Installation quality matters, too. Even a premium belt may fail after incorrect tensioning or pulley alignment. This is where product claims need careful review. Some information remains difficult to compare across brands, especially when testing methods differ. Readers should verify specifications, certifications, warranty terms, and application guidance before purchasing. The following manufacturers provide a useful starting point, not an absolute verdict.
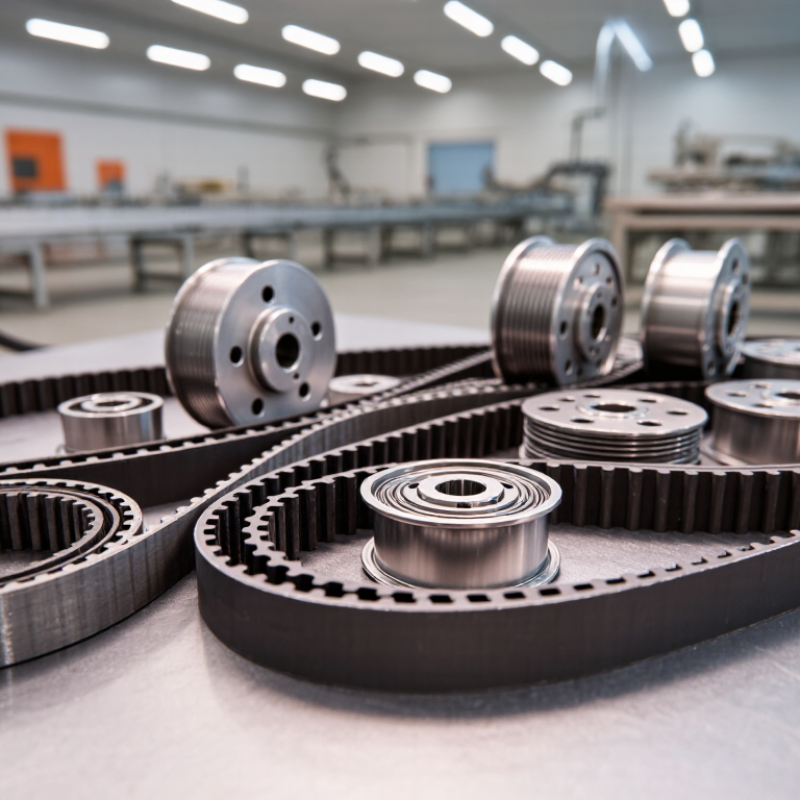
Table of Contents [Hide]
Rubber Timing Belts: Definition, Structure, and Key Functions
Rubber timing belts are toothed power-transmission components that synchronize rotating shafts. Unlike smooth belts, their teeth engage with matching pulley grooves. This positive engagement limits slipping during operation. In engines, packaging machines, and automated equipment, timing accuracy can be critical.
A typical belt contains a rubber body, embedded tensile cords, and molded teeth. The rubber compound provides flexibility and resistance to heat, oil, and wear. Tensile cords carry the pulling load, often using fiberglass, aramid, or similar reinforcement. Tooth facing materials reduce friction and protect the tooth profile. Small dimensional errors matter. A belt that looks acceptable may still create vibration, noise, or timing drift.
Tips: Check tooth wear, edge damage, surface cracks, and unusual dust during maintenance. Confirm the correct pitch, width, length, and pulley profile before replacement. Keep tension within the equipment maker’s specification; excessive tension can damage bearings. Clean installation is important because grit can alter tooth engagement. From practical inspections, alignment is often overlooked, although it strongly affects service life. No belt lasts forever. Temperature, contamination, shock loads, and poor storage can shorten its working period. A careful inspection record is more reliable than appearance alone, yet even experienced technicians should question assumptions when operating conditions change.